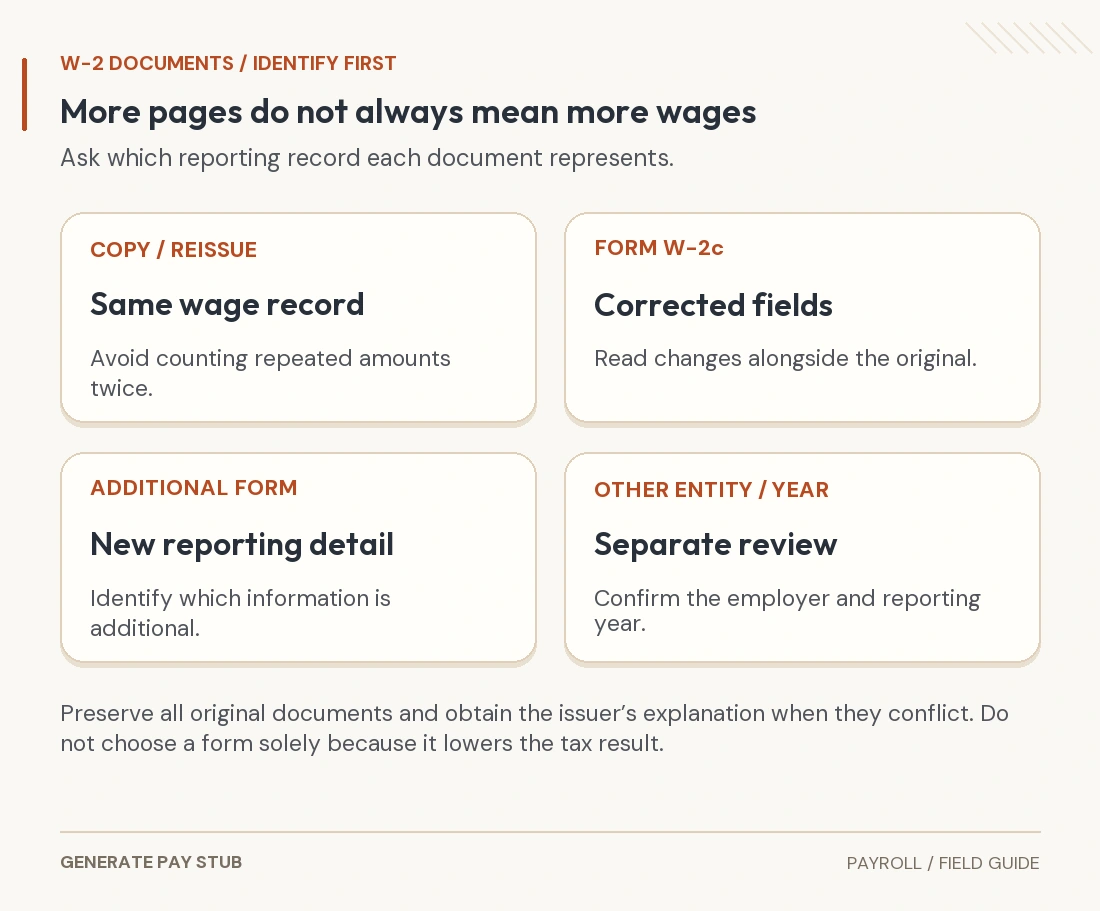
Two W-2 documents from the same employer do not automatically mean two sets of wages. They may be copies of one record, a replacement, a correction or forms carrying distinct information. Identify what each document represents before entering amounts into tax software.
This guide explains the review using federal W-2 reporting concepts and fictional figures. It does not determine whether an unfamiliar form is valid. Ask the employer to resolve inconsistent records, and use the instructions for the tax year actually shown on the forms.
Start with the tax year, employer identity and document type
Put all the documents side by side and compare the tax year, employer name/EIN, employee information, form type and amounts. Check whether a page says Copy B, Copy C or Copy 2, whether it is reissued, and whether a W-2c identifies a correction.
A W-2 packet contains copies for different uses. The IRS filing overview distinguishes employee copies from the federal SSA submission and any state/local copy. Having several copies in a packet is not evidence of several payments.
Also check for a different legal employer or reporting year. The same workplace brand can be associated with different employing organizations. A changed EIN calls for an explanation of the actual records; it should not be ignored or treated as proof of fraud solely from that difference.

Is a duplicate or reissued W-2 additional income?
A replacement copy can reproduce the same wage information. The IRS W-2 instructions describe reissued employee statements separately from another original wage report. An electronic replacement need not carry the same printed reissue label, so check the content and employer confirmation.
Suppose the original employee copy reports $54,000 in box 1 and $3,200 in box 2. A replacement reproduces those same facts. The example still contains $54,000 of wages and $3,200 of withholding, not $108,000 and $6,400.
Keep one organized set with the reason for the replacement. If the forms differ, stop treating the later file as a simple duplicate until the issuer explains the differences. A later download date is not enough to identify the controlling record.
How is a W-2c different from an extra W-2?
The official W-2c identifies the year/form being corrected and provides previously reported and correct information for affected fields. It is not a second wage payment to add to the first. A field not being corrected is not automatically zero.
| Field | Original information | Corrected information |
|---|---|---|
| Box 1 wages | $54,000.00 | $55,800.00 |
| Box 2 federal withholding | $3,200.00 | — |
Assume only box 1 is corrected to $55,800 and box 2 is unchanged. The dash in this teaching table means no correction to that field; it does not represent a new withholding amount. In this example, use corrected wages of $55,800 with the unchanged $3,200 withholding, following the filing software’s W-2c procedure.
The wage change is $1,800, but neither $1,800 alone nor $109,800 is the final wage total. Preserve the original and corrected documents together. For paper or electronic filing, follow the applicable original/W-2c submission instructions rather than inventing a combined employer form.
Can the employer legitimately issue additional forms?
Yes. The IRS instructions allow more than one W-2 where needed to report additional information, including extra coded items or state/local detail. The purpose is not to report the same federal tax data twice. Ask which fields are additional and which are repeated identification or reference information.
For a real employer-specific example, the Interior Business Center’s FAQ separates duplicate-copy requests from correction requests. Follow your own employer’s process; the contact routes and turnaround described for that organization are not a nationwide service promise.
Do not blindly add all state wages across every copy to derive federal wages. The state/local fields and federal wage fields answer different reporting questions. An additional state-information page may not represent another federal wage amount.
What should you ask payroll when the forms conflict?
- Are these copies of the same report, corrected information or separate reportable records?
- Which tax year and employing entity does each form cover?
- Which dollar fields are new, which replace earlier fields and which are unchanged?
- Has the employer issued an official correction where needed?
- Who can explain how the records reconcile to the year’s payroll?
Send the exact discrepancy through the employer’s secure route. For example: “One box 1 shows $54,000 and another shows $55,800. Please confirm the relationship and provide the official correction or additional-record explanation.” Do not post the full forms publicly.
The IRS incorrect/missing-W-2 guidance starts with requesting correction from the employer and describes further steps if the problem remains unresolved. Follow the current year’s instructions and filing deadline process; do not select whichever form gives a preferable refund.
What if you already filed before receiving the corrected form?
Compare the correction with the figures actually used on the return. The W-2c employee instructions say a correction that changes U.S. income tax requires an amended return and address Medicare-related corrections separately. Review federal and any state consequences rather than assuming every informational change has the same effect.
If two identical copies were accidentally entered as separate wages, review the filed return and the proper amendment process. Our Form 1040-X guide explains amendment records; it does not decide the treatment of an unresolved employer discrepancy.
Do not discard a notice or corrected record because the original return has already been accepted. Acceptance of a return and accuracy of the underlying wage information are separate questions.
Common questions about two W-2s
Should I enter each employee copy separately?
No additional wage record is created merely by receiving copies for different filing uses.
Does a blank W-2c field replace the original amount with zero?
Not automatically. Determine which fields are actually being corrected and retain unchanged information as appropriate.
Does an unfamiliar EIN prove the form is wrong?
No. Ask for the employer-entity explanation and compare the supported records.
Can I choose the W-2 with lower wages?
No. Resolve the record relationship and report the correct supported information under the applicable instructions.