Use the New York paycheck calculator in layers: set federal elections, enter IT-2104 state allowances, review Paid Family Leave coverage, then account for any local withholding and excluded deductions. The New York State income tax line is not a combined New York State, New York City and Yonkers calculation.
This 2026 guide follows a fictional $104,000 salary paid weekly. It checks the state withholding worksheet and the PFL annual cap, and explains why the average payment estimate can differ from both the first and last payments of the year.
Set up the New York paycheck calculator
Open the free New York paycheck calculator, choose 2026 and enter $104,000 annual gross wages. Select Weekly to model 52 payments of $2,000 each. This is a full-year wage input, not a field for one week’s pay.
For this controlled example, choose Single federally, with no multiple-jobs setting, credits, other-income adjustment, deduction adjustment or extra federal withholding. In the state section, choose the Single/head-of-household/higher-single-rate election, one New York STATE allowance and zero extra state withholding per payment. Use standard PFL coverage.
Assume one employer, ordinary covered wages for the full year and New York as both residence and work state. The example assumes no applicable local withholding, no benefits or other deductions, and all gross wages in the relevant federal, FICA, state and PFL wage bases. Its initial result is before any excluded disability contribution.
The 2026 IT-2104 instructions explain the state certificate and separate residency, marital and allowance information. A modern federal W-4 has no allowance count to copy automatically into the New York state field. Calculator settings also do not submit a signed IT-2104 to payroll.
Read the annual result and weekly average with their limits
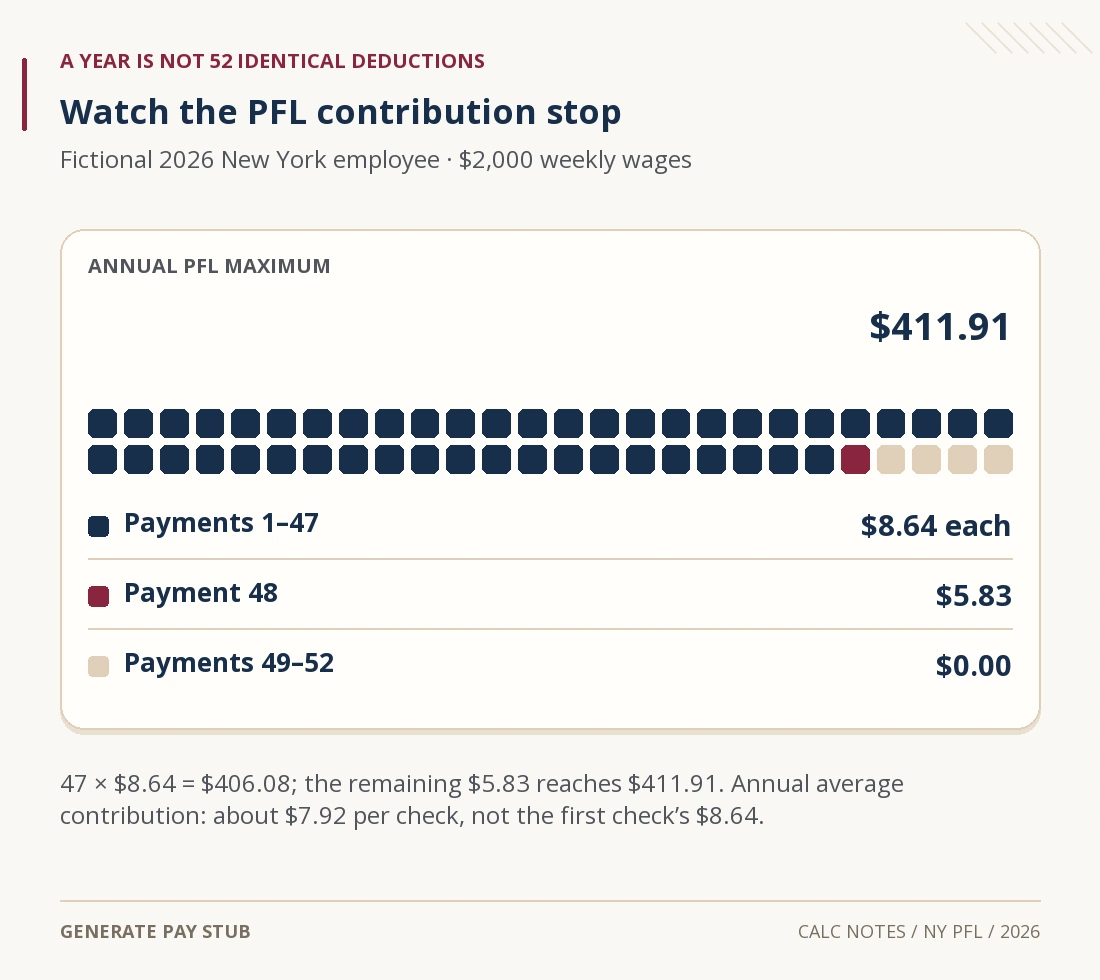
The checked live result includes $411.91 of PFL contributions across the modeled year. Because PFL reaches its cap before the final payment, the result’s average-per-check view is not a claim that every payment has the same deduction.
| Component | Annual projection | Average per payment |
|---|---|---|
| Gross wages | $104,000.00 | $2,000.00 |
| Federal income tax withholding | $14,049.88 | $270.19 |
| New York STATE withholding | $5,072.08 | $97.54 |
| Employee Social Security | $6,448.00 | $124.00 |
| Employee Medicare | $1,508.00 | $29.00 |
| New York Paid Family Leave | $411.91 | $7.92 |
| Estimated net before omitted items | $76,510.13 | $1,471.35 |
The annual cash check is $104,000 − $14,049.88 − $5,072.08 − $6,448 − $1,508 − $411.91 = $76,510.13. Divide by 52 to get the unrounded weekly average, then round for display. Multiplying the already-rounded $1,471.35 average back by 52 introduces a few cents of display rounding.
These wages are below the 2026 Social Security ceiling and the employer’s Additional Medicare trigger. For the federal income tax component, the federal calculator guide explains the separate modern W-4 method.
Verify the $97.54 state withholding amount
The tool uses an annualized New York State payroll method. In the official 2026 NYS-50-T-NYS publication, the annual Single deduction allowance is $7,400 and each withholding allowance contributes another $1,000 reduction to the worksheet wage amount.
For this example, $104,000 − $7,400 − $1,000 = $95,600 of annual net worksheet wages. The applicable annual row gives $4,190 + 5.9% × ($95,600 − $80,650) = $5,072.05. Dividing by 52 gives $97.5394…, which rounds to $97.54 per payment. Summing the 52 rounded amounts produces the tool’s $5,072.08 annual withholding projection.
Those are payroll worksheet figures, not a calculation of your return’s taxable income or effective tax rate. The $7,400 adjustment is already part of the payroll method; do not enter it again as an additional deduction. Period-specific permitted methods can produce small differences from the annualized approach.
The tax department’s 2026 withholding update confirms separate New York State, NYC and Yonkers publications. State allowances or extra state withholding do not calculate a missing local amount.
Follow Paid Family Leave through its annual maximum
The official 2026 PFL update sets the employee contribution rate at 0.432% of wages per payment, with a maximum annual contribution of $411.91. This contribution ceiling is separate from Social Security’s wage base and from PFL benefit limits.
For $2,000 of covered wages each week, $2,000 × 0.432% = $8.64. After 47 modeled payments, contributions total $406.08. The next payment needs only $5.83 to reach $411.91. The final four payments in this 52-payment example have no further PFL contribution.

With the other modeled deductions fixed, estimated net before omitted items is $1,470.63 on each of the first 47 payments, $1,473.44 on payment 48 and $1,479.27 on payments 49–52. That explains why the displayed $1,471.35 annual average is not the first week’s deposit estimate.
Actual coverage, approved waivers, employer-paid contributions or a different funding history can change the calculation. A coverage dropdown models your selection; it does not establish eligibility or approve noncoverage. This example begins at the start of the year with no earlier contributions to reconstruct.
Handle local withholding and disability as separate questions
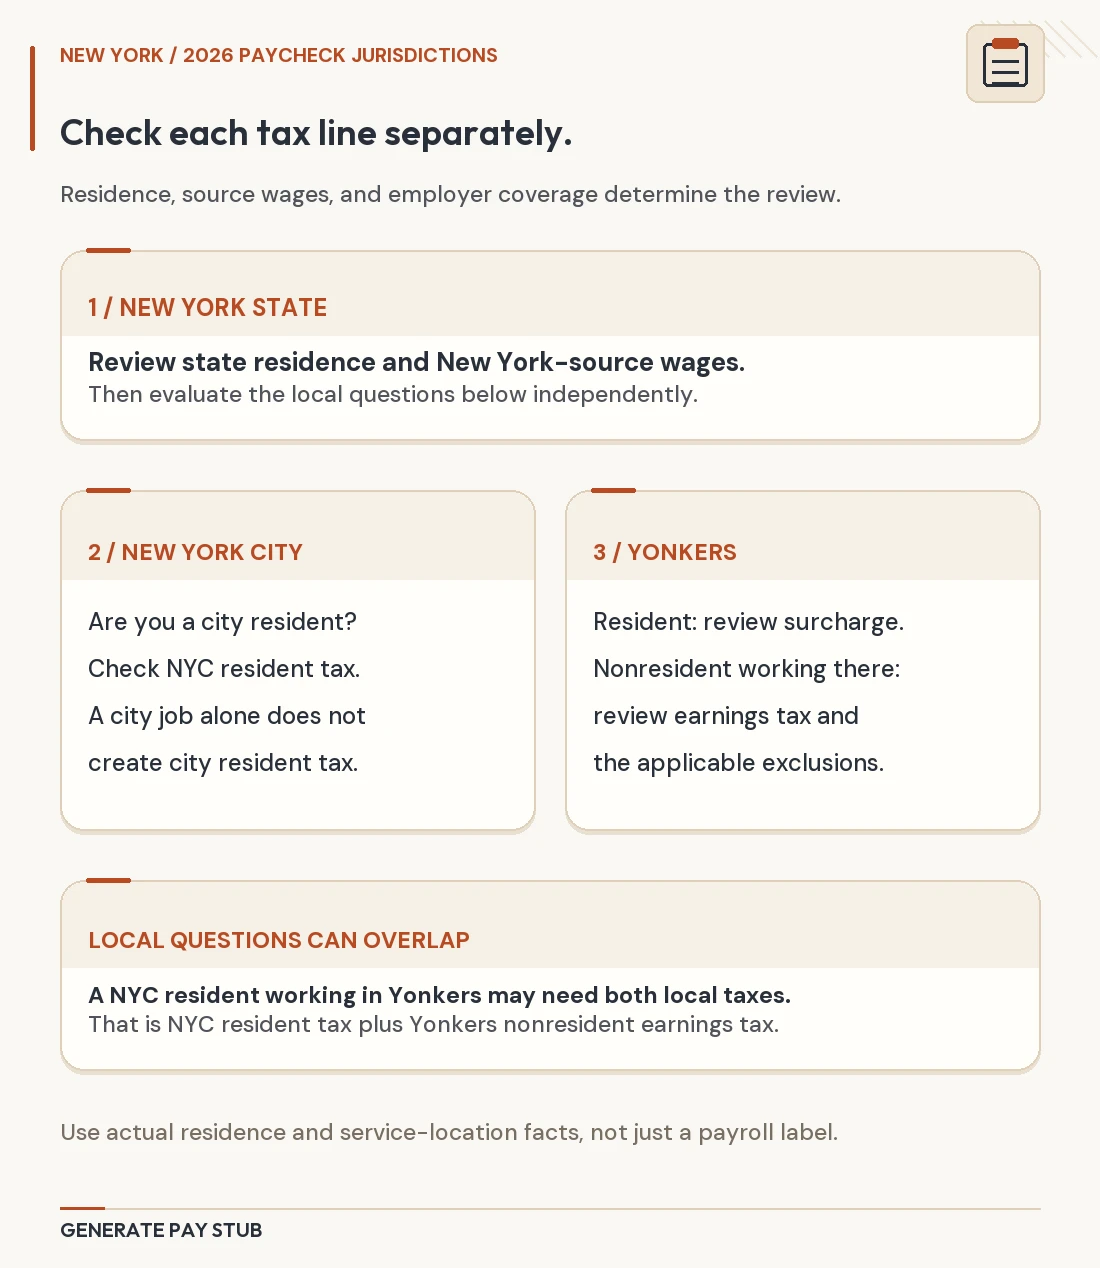
NYC and Yonkers require a local amount when applicable
The reviewed state page does not ask for enough city and residency information to calculate NYC or Yonkers withholding automatically. Its known local-withholding field accepts an annual dollar amount, rather than a city rate. Obtain the correct amount using payroll records and the applicable official tables, then supply it if it belongs in your projection.
A zero left in that field means no local cash withholding has been included in this estimate. It is not a determination that a NYC resident, Yonkers resident or affected worker owes no local withholding. Our New York pay-stub guide explains those separate lines.
NY disability is excluded from the automatic estimate
The live result explicitly lists NY disability among excluded items. The Workers’ Compensation Board’s disability guidance says an employer may collect an employee contribution of up to 0.5% of wages, capped at $0.60 per week. It is not a second PFL contribution, and employee sharing is not mandatory in every arrangement.
If payroll confirms an actual $0.60 cash deduction on all 52 payments, its annual amount is $31.20. As a checked budgeting illustration, adding that already-determined amount to the tool’s other annual cash-deduction field reduces annual net from $76,510.13 to $76,478.93, while the calculated tax lines stay unchanged. This is a manual known-amount adjustment, not an automatic disability premium or coverage calculation.
Recognize the projection’s boundaries
The model starts from one full year of same-state ordinary employment and equal scheduled gross payments. It applies the selected table revision across the projection, rather than rebuilding earlier payments under different revisions. Weekly means the standard 52-period assumption; verify the employer’s actual calendar.
Separate wage bases, pre-tax benefits, tips, bonuses, special exemptions, cross-border work and a partial employment year can require a different calculation. Known annual local and other cash deductions do not alter taxable wages. If you are testing a benefit, those fields do not supply its tax treatment.
Use the output as a traceable planning estimate. Keep the year, wage amount, frequency, certificate selections, coverage assumptions and omitted items together. For a statement mismatch, compare each component rather than assuming the annual-average net is the amount every payment must show.
New York paycheck calculator questions
Does one state allowance subtract $1,000 of tax?
No. In this method, the allowance reduces the annual worksheet wage amount by $1,000. The withholding effect depends on the applicable schedule and rounding.
Can I add NYC withholding to the state allowance count?
No. An allowance count is not a local dollar amount. Review the separate city rules and supply the known annual local withholding where appropriate.
Why does PFL stop even though wages continue?
The contribution has its own annual maximum. Once the modeled contributions reach $411.91 in this 2026 example, later covered payments add no further employee PFL amount.
Where are the other state calculators?
The free paycheck calculator directory links the state and DC tools. Each state has different certificate and employee-program assumptions to review.
New York 2026 sources, live controls and two complete calculator runs checked November 6, 2026. The examples remain before any items not explicitly included.