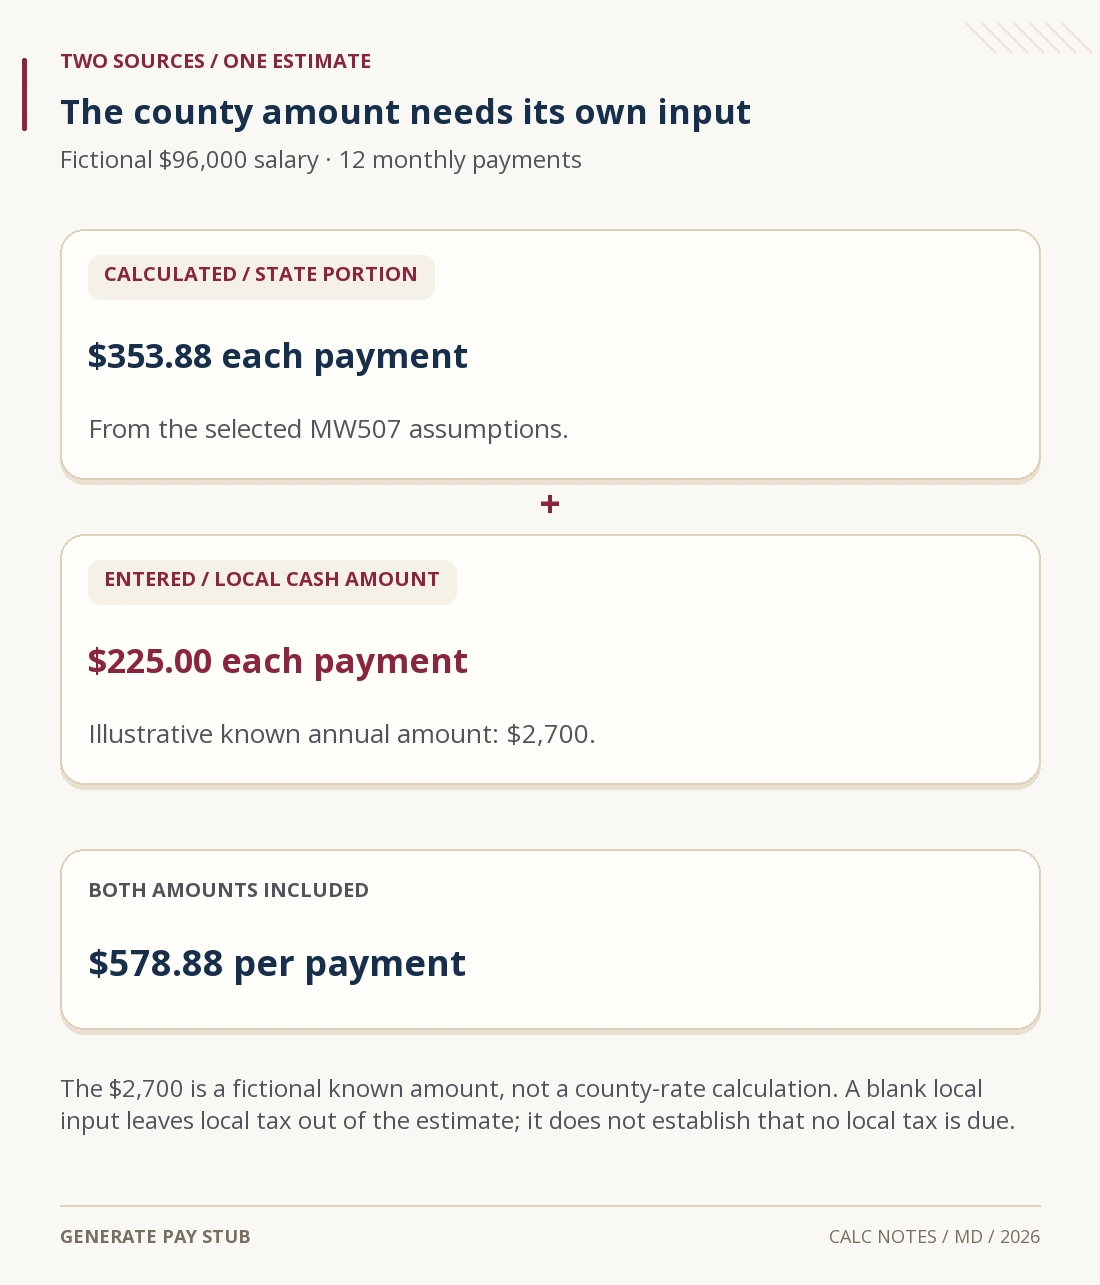
The Maryland paycheck calculator estimates the state income-tax portion, but it does not choose or calculate a county or Baltimore City tax rate. To include local withholding, enter a supported known annual dollar amount in its local field. Leaving that field at zero leaves local withholding out of the estimate; it does not establish that no local tax applies.
This guide checks a fictional $96,000 Maryland salary, then compares the result before and after adding an illustrative $2,700 annual local amount. The purpose is to show exactly which number is calculated and which number must come from another reliable source.
Understand the state/local boundary before using net pay
Open the free Maryland paycheck calculator. Its Maryland controls cover the MW507 withholding group, certified exemptions and additional state withholding per payment. There is no county-selection input in this tool.
The official 2026 employer guide includes combined state and local schedules. A published combined percentage must therefore be interpreted in its local-rate context. The state-only figure in this website’s estimate is not the entire combined withholding an employer may need to collect.
The Comptroller’s own withholding calculator asks for county of residence, along with wages, exemptions, frequency and filing status. Its nonresident instructions also identify cases requiring the work county instead. That county information is important; a generic wage figure cannot determine the correct local treatment by itself.
Enter a fictional 2026 monthly scenario
Select 2026, $96,000 annual gross wages and Monthly. Twelve $8,000 payments result. Choose federal Single with no multiple-jobs adjustment, credits, other income, deduction adjustment or extra federal withholding.
For Maryland, use the Single/married-separate/dependent withholding group, one certified MW507 exemption and zero extra withholding. Begin with zero known annual local withholding and zero other cash deductions solely to isolate the state portion. We add an illustrative local cash amount in the next run.
Assume a full year with one employer, Maryland residence and work, ordinary wages and no benefit adjustments. Federal, FICA and state wage bases all equal gross in this example. The employee is assumed to be entitled to the selected exemption.
The 2026 MW507 certificate supplies the actual exemption claim and per-period extra withholding. Its worksheet can adjust the claim for income and other circumstances. Enter the certified result, rather than replacing it with an unsupported household count.
Check the $353.88 state-only deduction
The projection uses the annual payroll standard deduction of $3,400 and $3,200 for one certified exemption. The annualized wage amount for this state calculation is $96,000 − $3,400 − $3,200 = $89,400.
For this withholding group and amount, the modeled state portion is 4.75%. It produces $89,400 × 4.75% = $4,246.50 before conversion to twelve payments. Dividing by 12 gives $353.875, rounded to $353.88 per payment. Adding those twelve rounded amounts gives $4,246.56 for the annual projection.
This method extracts the state component from the published combined schedule. For example, the guide’s annual first bracket in the 2.25% local section is 7.00%; subtracting that local component leaves 4.75%. It does not mean every employee should use a 2.25% county rate.
The payroll standard deduction used here should not be replaced with a different annual-return deduction. Nor should the 4.75% sample calculation be treated as a complete Maryland tax-return rate schedule. The Comptroller’s employer-withholding guidance explains that withholding tables disregard marginal state rates below 4.75%.
Add a known local amount without inventing a county rate
For the second test, assume payroll has separately supplied an annual local withholding amount of $2,700 for this fictional scenario. Enter 2700 in the known annual local field. Do not enter 225 there: $225 is the corresponding monthly amount.
The $2,700 is an illustrative input, not a local-tax calculation, named county rate or recommended withholding election. A real comparison needs a supported figure for the worker’s jurisdiction and circumstances.

The local cash input leaves the computed federal and Maryland state figures unchanged in the checked run. It reduces annual net by exactly $2,700, or $225 on the monthly average. It does not reduce taxable wages or cause the calculator to recalculate the local tax.
Do not enter the entire combined state-and-local deduction in the local field. That would count the state portion again. Obtain the local component separately or carefully reconcile a combined figure with payroll before entering it.
Reconcile the result with and without the supplied local amount
| Annual component | Local omitted | Known local entered |
|---|---|---|
| Gross wages | $96,000.00 | $96,000.00 |
| Federal income tax withholding | $12,290.04 | $12,290.04 |
| Maryland state portion | $4,246.56 | $4,246.56 |
| Social Security | $5,952.00 | $5,952.00 |
| Medicare | $1,392.00 | $1,392.00 |
| Local cash amount entered | $0.00 | $2,700.00 |
| Estimated net | $72,119.40 | $69,419.40 |
For the second run, the average monthly net is $69,419.40 ÷ 12 = $5,784.95. Its cash check is $8,000 − $1,024.17 federal − $353.88 state − $496 Social Security − $116 Medicare − $225 local = $5,784.95.
When local withholding is omitted, the corresponding result is $6,009.95 monthly. The $225 difference demonstrates the input’s cash effect. It does not establish which result matches an actual Maryland paycheck until the local amount has been verified.
Find the missing payroll information before relying on the estimate
Collect the actual MW507, current state and local withholding lines, county or Baltimore City information, taxable wage bases and the pay schedule. If the statement has one combined Maryland deduction, ask payroll to identify its components or method rather than guessing a percentage from the combined dollars.
An amount copied from one unusual payment may not be an appropriate annual local input. Confirm whether the figure reflects a regular schedule, bonus, partial period, changed residence or extra withholding. The calculator assumes the selected annual conditions remain in place; it does not reconstruct a residence change during the year.
MW507 has specific nonresident, reciprocal-state and military-related provisions. A state selection on this website does not determine eligibility for those claims. Use the certificate’s applicable instructions and the employer’s process instead of treating zero local input as an exemption request.
For federal settings, the W-4 calculation guide can help isolate a change. For a real deposit difference, the gross-to-net checklist helps reconcile the statement without mixing tax adjustments and cash deductions.
Check year, coverage and benefit limitations
The official Maryland FAMLI contribution page currently schedules contribution collection to begin in January 2027. This 2026 projection therefore does not add a FAMLI employee contribution. Use the applicable year’s rules when checking a later payment.
Other benefits, retirement deductions and employer arrangements still matter. The tool does not build separate federal and state wage bases for every plan. Its annual other-deductions field is a cash adjustment, not an instruction to calculate pre-tax treatment.
The reviewed Maryland result has no additional supported statewide employee program deduction. That limited result is not evidence that a worker has no other deductions. It also does not calculate final household tax, credits, a return balance or the full employer payroll cost.
Keep the year and payroll period attached to every comparison. A biweekly estimate uses 26 payments, whereas semimonthly uses 24. Copying a monthly amount into an annual field or selecting the wrong schedule can create a larger error than a one-cent rounding difference.
Maryland paycheck calculator questions
Does the Maryland state line include my county tax?
No. In this tool, it is the state portion. Include an independently supported local amount in the separate annual cash field.
Should I enter my county percentage in the local field?
No. That field expects annual dollars. It does not convert a county rate into the amount due.
Why is the annual state result six cents above my annual shortcut?
The projection sums twelve rounded $353.88 payments. The unrounded annual calculation gives $4,246.50 before that period rounding.
Can I use a result with no local amount as my final budget?
Only after establishing the local treatment. An omitted deduction can overstate available cash, even when the state-only arithmetic is correct.
Maryland 2026 primary references and both live calculator runs checked November 6, 2026. The $2,700 local input is fictional and does not represent a calculated county obligation.