The Georgia paycheck calculator needs a G-4 letter, total allowances and the payroll-table revision that matches the scenario. The revised 2026 calculation changes both the percentage and the deduction. Applying the new percentage to the old deduction will not reproduce the result.
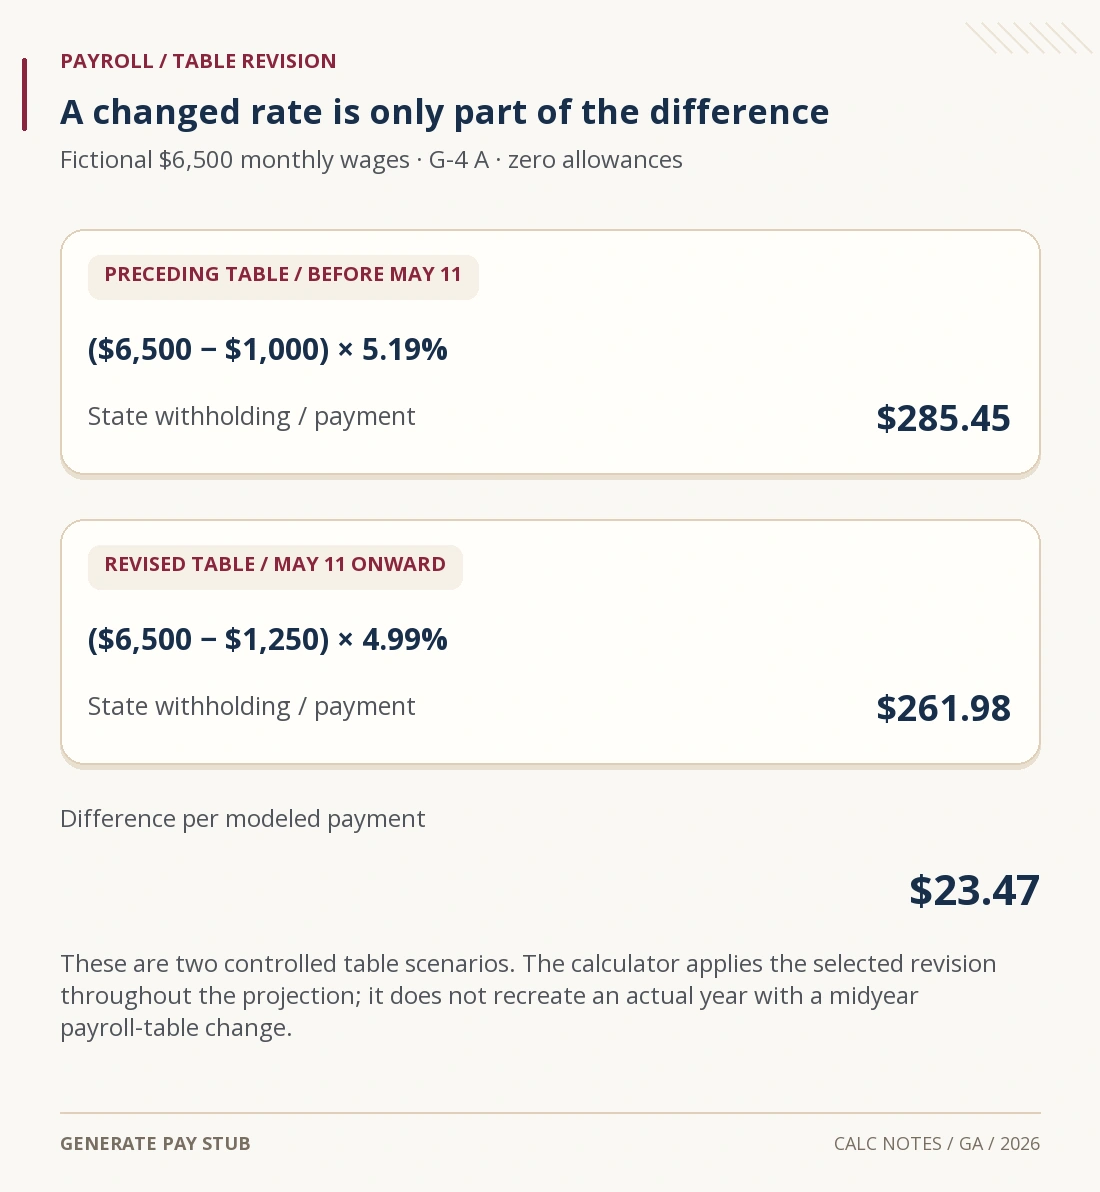
This walkthrough follows a fictional Single employee earning $78,000 over twelve payments. Two live runs isolate the table choice: revised-table state withholding is $261.98 monthly, compared with $285.45 under the preceding table.
Understand why Georgia has a dated table choice
The September 2026 employer guide explains that the tax-law change is retroactive for the tax year, but employers continued 5.19% withholding before the change and could begin 4.99% withholding May 11, 2026. Revised annual standard deductions are $15,000 for Single, Head of Household and Married Filing Separately, and $30,000 for Married Filing Jointly; the dependent deduction became $5,000.
The Georgia paycheck calculator exposes preceding and revised table selections. Its annual model applies whichever one you choose to every modeled payment. Neither option automatically combines the employer’s earlier and later payroll deductions.
Read the letter and allowance count from G-4
The current Form G-4 separates marital-status letters, dependent allowances, worksheet-based Georgia adjustment allowances and additional dollars. Line 7 combines the dependent and adjustment allowance counts.
A means Single; B covers Married Filing Separately or jointly with both spouses working; C is joint filing with one spouse working; D is Head of Household. Do not assume every married employee uses C. The form requires the adjustment worksheet when claiming those additional allowances.
Do not add a personal allowance for yourself. The state table already supplies its applicable standard deduction, including when total allowances are zero. Extra dollars are authorized per payment, rather than treated as an annual allowance count.
These are certificate inputs. Testing a value online neither establishes eligibility to claim it nor sends a signed form to payroll.
Set up a $6,500 monthly salary test
For the reviewed run, select 2026, enter $78,000 annual wages and choose Monthly. Federal status is Single, the multiple-jobs box is off and federal W-4 adjustment amounts are all zero.
For Georgia choose A, zero line 7 allowances, revised table and no additional withholding. This isolated test supplies no annual local-tax amount and no miscellaneous cash deduction.
Assume the employee lives and works in Georgia all year for one employer. Gross pay also equals federal, FICA and state taxable wages, with no pre-tax benefits or special earnings. These assumptions allow a clean comparison of two table selections.
For the second test, change only the table revision to preceding. That single-variable comparison is useful when checking why an estimate changed; it is not a recommendation to use an obsolete table for a current payroll.
Compare the two monthly computations
Under the revised percentage method, the Single monthly deduction is $1,250. With no allowances, the sample base is $6,500 − $1,250 = $5,250. Multiply $5,250 by 4.99% to obtain $261.975, rounded to $261.98.
The preceding-table control uses a $1,000 monthly deduction in this scenario. Its calculation is ($6,500 − $1,000) × 5.19% = $285.45. The $23.47 difference reflects both changed inputs.

| Comparison measure | Preceding selection | Revised selection |
|---|---|---|
| State deduction per payment | $285.45 | $261.98 |
| State withholding across 12 payments | $3,425.40 | $3,143.76 |
| Estimated net each month | $5,023.13 | $5,046.60 |
| Estimated net across 12 payments | $60,277.56 | $60,559.20 |
Across twelve rounded monthly deductions, the state withholding difference is $281.64. Federal withholding and FICA stay unchanged because the comparison changes no federal input or taxable wage.
Reconcile the revised take-home estimate
| Component in this model | Annual total |
|---|---|
| Salary before deductions | $78,000.00 |
| Federal income tax withheld | $8,330.04 |
| Georgia income tax withheld | $3,143.76 |
| Employee Social Security | $4,836.00 |
| Employee Medicare | $1,131.00 |
| Estimated net earnings | $60,559.20 |
Each modeled payment reconciles as $6,500 − $694.17 federal − $261.98 state − $403 Social Security − $94.25 Medicare = $5,046.60. This figure includes no unentered insurance, retirement, garnishment or other employee deduction.
The annual state total is $261.98 × 12 = $3,143.76. A calculation that rounds only after multiplying the unrounded $261.975 by twelve would give a different six-cent result. Follow the model’s payment-level rounding when checking its displayed annual sum.
Separate a full-year scenario from actual 2026 history
For an actual year containing a table change, assemble the payroll register or dated statements. Group deductions by the table, pay date, certificate and wages actually used. Add actual withholding already taken, then estimate remaining payments using their expected facts.
Do not describe twelve revised-table payments as the amount the employer necessarily withheld during 2026. The selected-table annual projection answers “what would this repeated setup produce?” It does not answer “what was already withheld before my payroll changed?”
Final Georgia tax and payroll withholding also serve different purposes. A retroactive return calculation does not imply that an earlier paycheck was calculated using a table that had not yet become available.
Review a real paycheck that differs from this example
First compare the pay schedule and taxable wage amounts. Biweekly has 26 modeled payments; semimonthly has 24. A different deduction can result from the schedule even when annual salary stays constant.
Then inspect the G-4 letter and total allowances, the revision selected and any per-payment extra dollars. Check federal elections independently using the federal W-4 calculator guide.
Known annual local withholding and other deductions are cash inputs, not automatic local tax calculations or pre-tax exclusions. Cross-state services, exemption claims, supplemental wages, varying benefits and midyear employment need more than this ordinary single-state model.
For a statement-level comparison, use the Georgia G-4 pay-stub guide. A free estimate does not create a payroll record, update the employer’s certificate or establish your eventual refund.
Georgia paycheck calculator questions
Should I claim one allowance just because I am Single?
No. Use the actual G-4 line 7 total; the calculator does not add a personal allowance.
Does the revised rate apply directly to gross wages?
Not in this method. Subtract the applicable table deduction and allowable allowance amounts before applying the percentage.
Does the table selector rebuild the midyear change?
No. It holds one revision constant across the full projection.
Does extra state withholding reduce federal taxable pay?
No. It changes cash withheld for the state; it is not a federal wage exclusion.
Georgia 2026 dated guidance, G-4 controls and both live examples checked November 6, 2026. All salary and household facts above are fictional.